Cars & vehicles
Car loan, novated lease or the home loan: the real cost of each on a $45,000 car
The home loan has the lowest rate and, over 25 years, the highest interest bill: about $46,000 on a $45,000 car versus $10,400 on a five-year car loan. Repaid in five years it is the cheapest. Each route, costed.
26 October 2026
6 min read
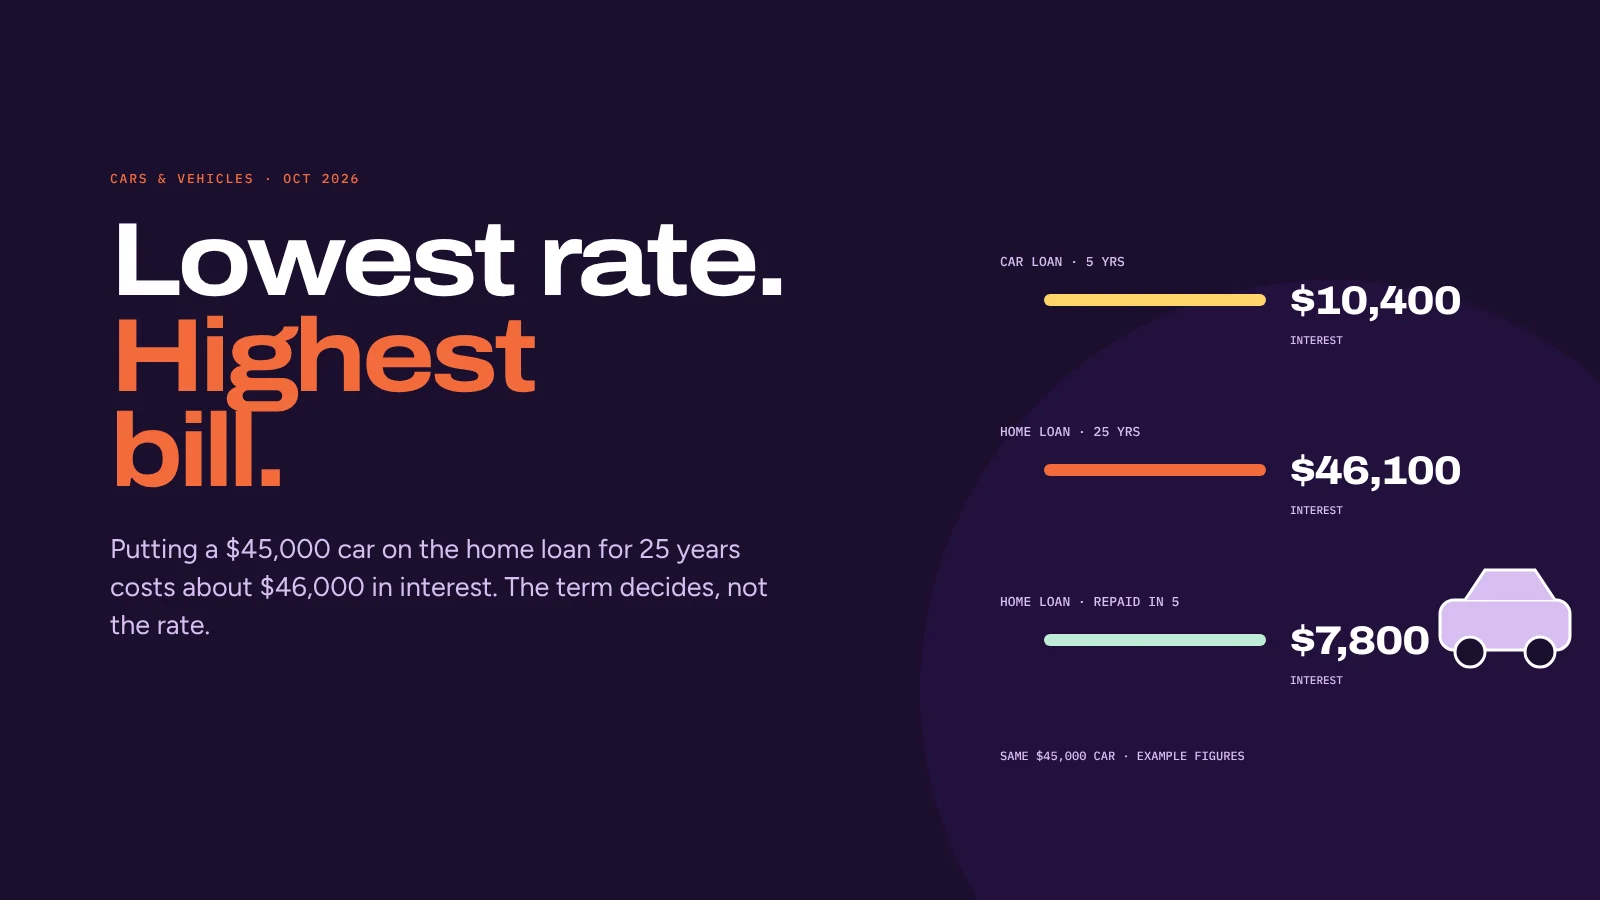
Putting a car on the home loan looks cheapest because the rate is lowest, but spread over the 25 years left on a mortgage it usually costs the most interest. A $45,000 car costs about $10,400 in interest on a five-year car loan and about $46,000 if it sits on the home loan for 25 years. The home loan only wins if you pay the car off over five years anyway. A novated lease is a different calculation again, driven by tax.
There are three common ways to pay for a car if you don't have the cash: a car loan, a novated lease through your employer, or the home loan, by redrawing, using an offset balance or topping up. The rate is the first thing people compare. It's the least useful number of the lot.
Here's how each route actually costs out on the same car, and when each one makes sense.
The same $45,000 car, three ways
These are example figures: a car loan at 8.5% over five years, and a home loan at 6.5%.
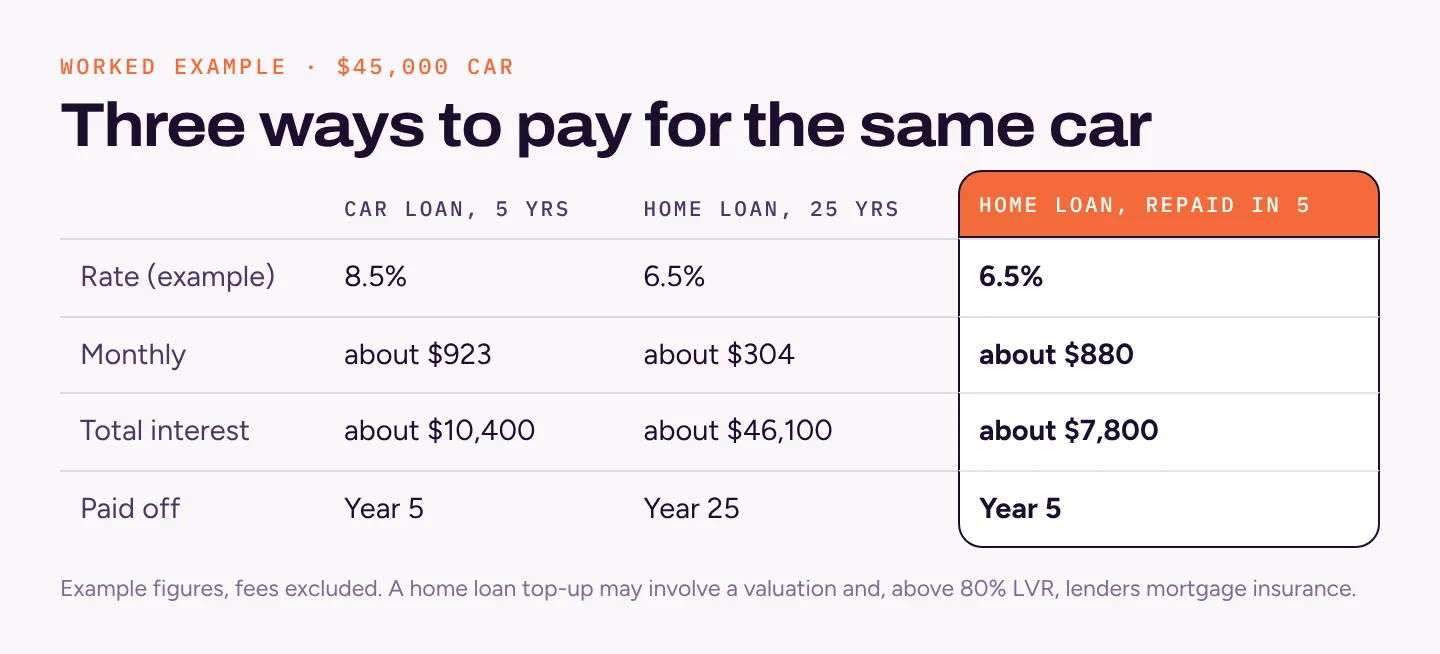
- Car loan over five years: about $923 a month, about $10,400 in interest, and the car is paid off in year five.
- Home loan over the remaining 25 years: about $304 a month extra, which feels painless, and about $46,100 in interest. You'd still be paying for this car long after you've sold it.
- Home loan, but paid off over five years: about $880 a month, about $7,800 in interest. This is the cheapest route, if you have the discipline to repay it on that timetable.
The lowest rate gives both the most expensive result and the cheapest one. What decides it is the term, which is where the low monthly figure on a home loan does its damage.
The costs people forget
A car loan usually has an establishment fee and sometimes a monthly fee, and both belong in the comparison. A home loan top-up can involve a valuation and, if it pushes the loan over 80% of the property's value, lenders mortgage insurance, which can wipe out the rate advantage on its own. A lease has its own administration fees. Ask for the total cost over the term for each option, not the rate.
How each one affects your next loan
The car loan costs you borrowing power. A lender will count the full monthly repayment as a commitment, which on our example is about $923 a month and, at today's assessment rates, about $100,000 or more off what you could borrow for your next home. I covered that in six levers that move your borrowing power.
A home loan top-up needs a fresh application and assessment, and lifts the loan balance and your loan-to-value ratio. Using redraw or an offset needs no application, but the money you take out was protecting you from interest at the home loan rate, and your buffer is smaller afterwards.
Where a novated lease fits
A novated lease is an arrangement between you, your employer and a finance company. Payments come mostly from your pay before tax, running costs can be bundled in, and fringe benefits tax applies to most cars. At the end there's a residual payment set by ATO guidelines, about 28% of the price on a five-year lease, so roughly $12,700 on our car.
For electric cars under the luxury car tax threshold, the FBT exemption makes a lease hard to beat. The government has announced the exemption will narrow from 1 April 2027, with EVs up to $75,000 keeping it until 31 March 2029 and existing leases keeping their treatment. Check where the legislation stands before you sign. For petrol cars, the saving depends on your tax rate and how much you drive, and it's often smaller than the brochure suggests once fees are counted. The full comparison for EVs is in EV novated lease or car loan, and the residual risk on cheap EVs in the balloon-payment trap.
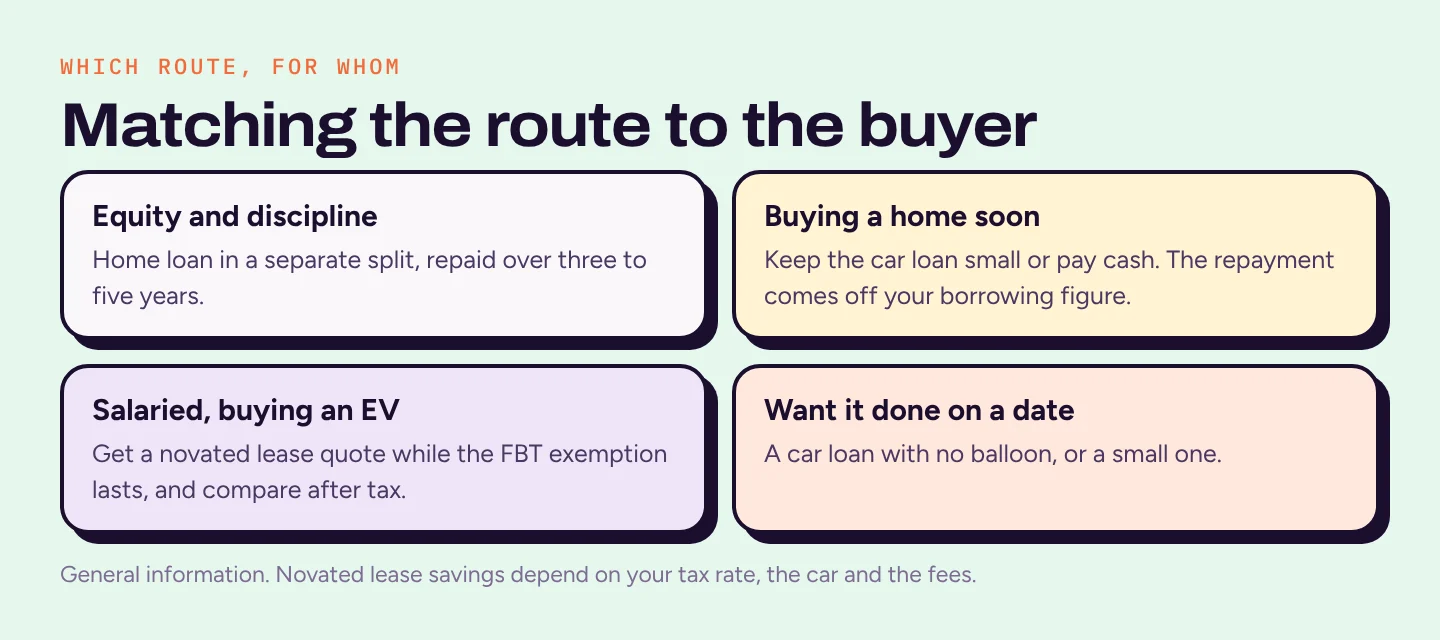
Which route, for whom
- You have equity and discipline: the home loan, in a separate split, repaid over three to five years. Cheapest interest, and keeping it separate stops it disappearing into the 25-year balance.
- You're buying a home in the next year or two: think about paying cash or keeping the car loan small, because the repayment comes off your borrowing figure.
- You're salaried, the car is electric and under the threshold: get a novated lease quote and compare the after-tax cost.
- You want the car paid off on a fixed date with nothing else attached: a car loan, ideally with no balloon or a small one.
Questions people ask
Is it cheaper to buy a car with my home loan?
Only if you repay it over a short term. Over the life of a mortgage, the lower rate is outweighed by decades of interest.
Does a car loan affect my borrowing power?
Yes. Lenders count the full repayment, and each $450 a month of commitments costs roughly $50,000 of borrowing power at today's assessment rates.
What happens at the end of a novated lease?
You pay the residual, refinance it, or trade the car in. If the car is worth less than the residual, you cover the difference.
Where to start
Our asset and vehicle finance page covers car loans, and the loan repayment calculator will compare any term. If you're deciding between routes, book a free 30-minute chat and bring the car's price and your last home loan statement.
Sources
- Moneysmart: car loans
- Moneysmart: salary packaging
- Canstar: car residual values
- ATO: electric cars exemption
Last reviewed 26 October 2026. This is general information only and isn't tax advice. It doesn't take your objectives, financial situation or needs into account. All figures are examples.
Want this applied to your numbers?
Articles are general information. A 30-minute chat with Suvidh and the team turns it into a plan for your situation: borrowing power, structure and the lender that fits.
Book a free chatRun the calculatorsWritten by the Cinch Loans team · Reviewed by Suvidh Arora, Chief solutions officer · About us
Keep reading
More from Cinch Insights.
Plain-English articles on home loans, refinancing, rates and the property market, written for Australian borrowers rather than for lenders.
Cars & vehicles
October 26, 2026
Car loan vs novated lease vs home loan redraw: real cost compared (2026) | Cinch Loans
The home loan has the lowest rate and, over 25 years, the highest interest bill: about $46,000 on a $45,000 car versus $10,400 on a five-year car loan. Repaid in five years it is the cheapest. Each route, costed.